Many people treat insurance as a set-it-and-forget-it purchase. They know they need coverage, so they shop around and buy a good policy, then assume it will protect them as long as they continue to make payments. But what people don’t realize is that their needs change over time, so your coverage needs to evolve over time to ensure that you don’t have coverage gaps or aren’t paying for insurance you don’t need. Here’s why you need to do a mid-year insurance review, what could prompt your policy needs to change, and lesser-known policies you should also pay attention to.
Why a Mid-Year Review Makes Sense
Halfway through the year is the best time to do a review on your insurance policies. You’re far enough along into the year to be past New Year’s resolutions, the kids are out of school, and annual enrollment is still a few months away.
A mid-year insurance review allows you to determine whether your current health insurance, HSA or FSA contributions, life insurance, disability coverage, and retirement plan still meet your needs. I also recommend clients use this opportunity to track where they stand with their other financial goals as well, like paying off debt, retirement plan contributions, and putting money into their emergency fund.
Without regular reviews, you risk being underinsured, overinsured, or paying for protection you no longer need. Your mid-year insurance review can save you money or avoid being surprised by a gap in your coverage.
What Could Prompt a Policy Change
None of us are the same person we were five years ago. For many people, your life looks vastly different today than it did a year go. Here are a few of the most common life events that should trigger a life insurance review:
- Getting married or divorced
- Having a new baby
- Buying a home
- Changing jobs or getting a promotion
- Starting a new business
- Major home renovations
- Purchasing a boat or an RV
- Kids graduating or turning 18
- Rising home replacement costs or a high-value purchase
I already bought life insurance after our first child was born. But when we got pregnant with our second child, I reviewed my coverage and added a second policy to reflect our growing family and my rising salary. The combination of the two policies ensured my family was protected in case I died prematurely.
The Core Insurance Policy Checklist
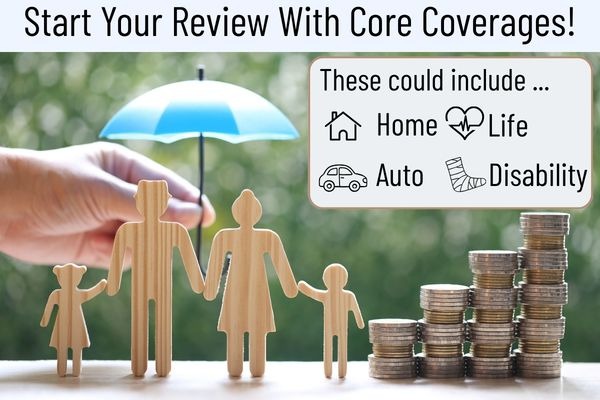
When doing a mid-year insurance review, start with the core coverages that protect the major areas of your life — home, auto, life, life, and income (disability). These policies cover the majority of situations where you may need to file a claim.
Homeowners Insurance
A home is one of the largest assets most people own. While you may not make changes to it on a regular basis, rising replacement costs may mean you need more coverage today than you did last year. If you’ve recently completed renovations, added a room, or made a major investment, like solar panels, a new roof, or a pool, then you need to review your coverages.
Replacing your roof, adding sprinklers, or other major upgrades could qualify you for better coverage or lower premiums with your insurer or a new one. Some insurers won’t cover homes with older roofs, outdated electrical, or other deficiencies.
During your mid-year insurance review, confirm whether your policy has replacement cost coverage or actual cash value. A policy with actual cash value coverage could leave you with a major financial loss, while replacement cost ensures that you’re fully protected. Review personal property limits as well to ensure your personal items are protected, including riders or floaters covering high-value jewelry, collectibles, and electronics.
Auto Insurance
Details that affect car insurance can change from year-to-year. Your age, miles driven, type of car, and where you live all impact auto insurance rates. In some states, even your credit score can have an effect on how much you pay.
When reviewing your auto policies, look for coverages that you can eliminate to reduce premiums. When you have multiple cars in your household, you might be able to eliminate rental car coverage. People who are working from home full-time or several days a week can reduce their annual mileage to save money.
If you’re driving an older car with a low value, consider whether it still makes sense to pay for comprehensive or collision coverage. After paying your deductible, there may not be much of a payout left to help you replace your vehicle. I tend to keep my vehicles for 9 to 10 years or more, so I drop collision coverage toward the end of my car’s life.
My wife got a new car after she was hit on the freeway. That was a good time to reevaluate policies to ensure we’re covered adequately. Additionally, many auto insurance companies price based on age, so last year’s policy may not be the right one going forward.
Life Insurance
Life insurance needs change over time. If you’ve had a recent life change, you may have too much or too little insurance coverage. Getting married, having a baby, or buying a house are key life moments where people buy additional insurance or their first life insurance policy. Even if you don’t change your death benefit, your beneficiaries may need updating to add a new baby or remove an ex-spouse. When our second child was born, updating who would split my life insurance proceeds was an immediate concern.
As your income increases due to promotions, large raises, or a career change, it’s important to review your death benefit to ensure it still meets your goals. A common rule of thumb is that your life insurance should be at least 10 times your annual income. You can extend this further by factoring in debt you want to pay off or future needs, like college tuition or caring for a disabled child.
Health Insurance
For people who get their health insurance through work, you can only change coverages once a year during open enrollment (unless you have a major life change, like marriage, baby, divorce, or spouse changes jobs).
But summertime is still the perfect time for a mid-year insurance review. This allows you to evaluate how your coverage is working, if you’re saving too much or too little in HSAs or Flexible Spending Accounts, or if you don’t have access to the doctors you want. HSA and FSA amounts can change each year, so it pays to plan ahead based on your expected spending. We try to max out our HSA each year to take advantage of its triple tax benefits — tax-deductible contributions, tax-free growth, and tax-free withdrawals for eligible expenses.
Future plans also should factor into the coverage you select during open enrollment. For example, if you plan on getting pregnant next year or can time when to have surgery.
Disability Insurance
Disability insurance is one of the most overlooked policies, but it can be one of the most important since it affects your ability to earn an income. Statistics say that the average 20-year-old has a 1 in 4 chance of becoming disabled at some point during their career. And the average length of a disability claim is three years.
During your mid-year insurance review, ensure that your disability benefit still matches your current salary. If you don’t have disability insurance, now may be the time to add this coverage to your portfolio. When I worked in the corporate world, signing up for disability insurance was an option during open enrollment. However, these benefits often didn’t replace your entire income, so even if you have disability benefits through work, you may need to supplement them with a small policy.
When reviewing your disability policy or shopping for insurance, make sure you understand the policy’s elimination period and benefit period. These factors not only impact your premium, but how much money you’ll receive if you need to file a claim.
Lesser-Known Policies That Also Need a Review
Aside from the major policies, it’s important to do a mid-year insurance review on other coverages you may have.
- Umbrella insurance: An umbrella policy is often tied to minimum underlying limits, so changes to auto or home coverage can also trigger the need for a review.
- Renters insurance: If you’ve moved to a new rental or your roommate situation has changed, your policy may need updating.
- Home-based business gap: Starting a new business can bring in extra income, but you may not be covered if you don’t update your homeowners insurance.
- Long-term care insurance: Rising costs for long-term care and changing financial strength of insurers may be a good reason to re-evaluate your coverage. Even if you’re not old enough to consider long-term care, it may be time to have the conversation with your parents.
- Pet insurance: At the end of each policy term, some providers can modify coverage by imposing additional exclusions, decreasing payout percentages, or increasing deductibles.
The Bottom Line
A mid-year insurance review is a smart way to ensure you have the coverage you need and aren’t paying for coverage you don’t. While you may decide to buy a new policy or increase coverage limits, reviewing your policies doesn’t necessarily mean that anything will change or that you need to pay more money. Block out 30 minutes to review your declaration pages with your spouse or a trusted friend. If you’re unsure what to look for, many independent insurance agents offer free reviews. Consider booking an appointment to get their opinion on your policies and what, if any, holes there are in your coverage.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- The American Institute of Architects Trust, Disability Insurance: Key Facts You Need to Know. Published February 2025.
- State Farm, Times to review your insurance. Published September 16, 2025.
- Allstate, Why You Need an Annual Insurance Review. Published February 2026.
- Progressive, What is a life insurance policy review? Accessed June 15, 2026.
- Nixon Peabody Trust Company, Insurance policy review: Assessing life, health, and property insurance coverage. Accessed June 17, 2026.