Life insurance is an affordable way to protect your loved ones by replacing your income, paying off debt, and covering future expenses. When you buy a life insurance policy, you expect the insurance company to pay out when you die. However, there are some situations where the insurance company will reduce the death benefit or void the policy altogether. Every life insurance policy has exclusions, and plenty of policies simply don’t provide as much coverage as families assume. Here’s what you need to know about the hidden gaps in life insurance, the fine print that can void your claim, and five ways to close the gaps before your family finds out the hard way.
Why These Gaps Matter More Than You Think
A life insurance policy is one of the few financial products you buy for others rather than yourself. Aside from policy loans and living benefits, most policyholders never find out whether their plan worked because they don’t pay out until you’ve died.
The job of getting money from the insurer falls to your beneficiaries at the worst possible moment. Not only are they dealing with the psychological and emotional trauma of losing a loved one, but they’re also struggling with the loss of your income. And they have no ability to go back to fix any mistakes you didn’t know you made when setting up your policy.
This is why I advise clients to involve their family in the process of buying their life insurance and reviewing it periodically.
There are two very different ways a life insurance policy can fall short.
- Claim denials. An insurer may deny a life insurance claim when something about the death or the original application falls into an excluded category.
- Inadequate coverage. The more common scenario is that the policy pays out exactly as promised. However, the death benefit amount was never enough to begin with.
I encourage all of my clients to review both of these risks every few years. Understanding where the gaps are allows you to fix them while you’re still young enough and healthy enough to qualify for a new policy.
The Fine-Print Exclusions That Can Void a Claim
Unlike other types of insurance that may have multiple claims over time, life insurance generally only has one payout event – when you die. For most policyholders and their beneficiaries, insurance companies pay out on life insurance claims without a problem. But nearly every policy has specific circumstances where a claim can be reduced or denied in full.
The Suicide Clause
Almost every life insurance policy includes a suicide clause. This clause excludes payouts if the policyholder dies by suicide within the first two years of the policy. In some states, this restriction is just for the first year.
After the initial exclusion window passes, the policy will pay out the full death benefit whether you died by suicide or any other cause of death. This exclusion window prevents people from buying a policy right before committing suicide. As someone who has written countless life insurance policies across multiple providers, it’s the one exclusion I’ve seen at every insurer I’ve worked with.
Crime and High-Risk Activity
Insurance companies can deny the claim if you die while committing a crime, such as during a robbery or other unlawful act. Your beneficiaries may not receive the death benefit if you have undisclosed high-risk hobbies that are excluded from coverage.
If you took up aviation, scuba diving, or motor racing after buying your policy and never told your insurer, a death connected to that activity could trigger a denial or a reduced payout. The exclusion for hobbies may not apply if you do them once, or even occasionally. These exclusions target people who regularly participate in risky activities that increase the likelihood of an early death.
Misrepresentation on the Application
This is the exclusion I spend the most time on with clients when applying for life insurance. People can control how much they volunteer on their application, and they often think that a “little white lie” won’t matter.
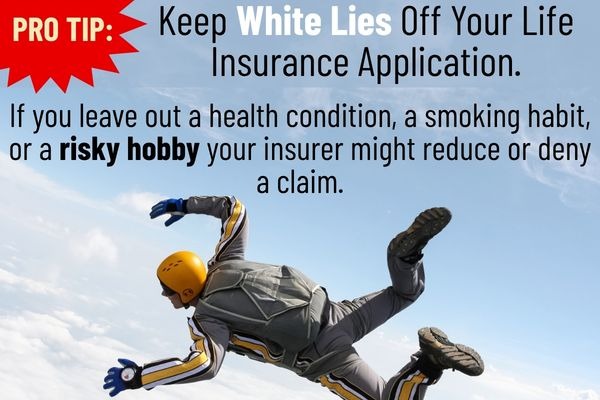
If you leave out a health condition, a smoking habit, or a risky hobby and the insurer discovers it after your death, they can deny the claim entirely or reduce the payout. This is true even if they don’t find out until much later or when processing a death claim.
In my experience, most misrepresentation issues aren’t intentional fraud. They’re an applicant who genuinely forgot a detail or didn’t think it mattered. However, it matters because an insurance company could deny the application entirely or require a higher premium to provide coverage based on your answers. In general, it’s best to disclose everything, even if you’re worried about paying more for your policy.
On the bright side, exclusions are locked in at the time you sign your policy. An insurer can’t add a new exclusion to your policy after you’ve already purchased it. So, if you’ve disclosed everything upfront and the insurer approves your application, they cannot deny a payout if you die due to a disclosed activity or health condition.
The Bigger Gap: Not Having Enough Coverage
Exclusions get most of the attention and make the most headlines, but I’ve seen far more families hurt because they didn’t have enough insurance rather than having a claim denied. Here are a few situations that may apply to you.
Relying Only on Group or Employer Coverage
Employer-provided life insurance is a nice benefit, but it shouldn’t be the only life insurance you own. Group coverage is tied to your job, and the premiums are based on the average age, health, and other demographics of your fellow employees instead of your own.
If you leave, get laid off, or retire, that coverage typically ends with your employment. In some cases, you may be able to keep your policy for a limited time after leaving or be subject to expensive conversion options that raise premiums even higher.
Outdated Coverage Amounts
Many people buy life insurance, check the box on their financial to-do list, and then never think about the policy again until someone dies. In reality, a policy that was more than adequate ten years ago may not come close to covering your family’s needs today.
Successive promotions at work, inflation, a new mortgage, additional children, or a spouse who left the workforce to raise kids can all quietly turn a well-sized policy into an underfunded one. This is why I recommend that clients recalculate their coverage needs every few years to account for any changes in their finances.
Periodic reviews don’t necessarily mean you need more life insurance. As the mortgage balance declines or kids turn into adults, you may actually be able to reduce your policy or let a term policy lapse rather than replace it.
Job Changes and Portability
Even when a new employer offers group life insurance, it may not match what you had at your last job. A new job with lucrative benefits may have a waiting period that leaves you exposed until you can start to participate. And coverage amounts, waiting periods, and conversion terms all vary by employer and by plan.
If your family’s financial security depends on that coverage, it’s worth confirming exactly what you’re getting with each job change instead of assuming it’s a like-for-like swap.
While employer coverage is often automatically approved (up to a maximum amount or multiple of your salary), it is often not adequate on its own. Consider buying a separate policy that you own to boost your death benefit to match your needs and provide coverage while waiting for your employer’s benefits to kick in.
How to Close These Gaps
You don’t need to overhaul your entire life insurance strategy to fix these problems. A few targeted steps go a long way.
- Disclose everything on your application. Health conditions, smoking or vaping, high-risk hobbies, and family history can affect your approval or premium. It’s better to have a “rated” policy and pay extra than to have your claim denied when your family tries to collect.
- Don’t rely solely on employer group life insurance. I recommend combining coverage from work with an individual term policy to achieve your desired death benefit. The term life insurance stays with you regardless of your job status, so your family isn’t left without financial protection if you leave your job.
- Recalculate your needs at every major life event. Marriage, a new child, a home purchase, or a significant change in income are all good triggers to reassess whether your current coverage amount still makes sense.
- Tell your agent about high-risk hobbies before you take them up. If you’re planning to get a pilot’s license or start racing, ask your agent directly how it affects your existing policy.
- Review your policy every three to five years. Even if you don’t have a major life event, your life insurance needs can change every few years. The rising costs of living, additions to your family, and shifting financial obligations can leave you with hidden gaps in coverage. A periodic review allows you to recognize those gaps and address them before they become something much bigger.
The Bottom Line
Exclusions and inadequate coverage are different problems with the same outcome: your family gets less than they were counting on when they need it most. They’re already emotionally traumatized by your death. Don’t let a denied claim or reduced payout add even more stress when your family is grieving. By disclosing your health status, family history, and hobbies during the application process, you can avoid denials when you pass away. Review your coverage every few years to determine if you need more or less coverage. Follow these steps to ensure the death benefit you’re paying is what your family actually receives when you’re gone.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- Ethos, What Does Life Insurance Not Cover? Published July 15, 2026.
- Gill Insurance Advisors, Does Life Insurance Cover Death During Extreme Sports? Published July 31, 2025.
- U.S. News, Life Insurance Exclusions. Published May 18, 2026.
- InsuranceBrokersUSA, Common Exclusions in Life Insurance Policies: Fine Print. Published September 4, 2025.
- Leavitt Group, Addressing Common Personal Insurance Gaps. Published November 15, 2024.
- Risk & Insurance Associates, Closing Gaps in Your Insurance Coverage. Published June 12, 2024.