When you become a Dad, your life changes in so many ways. In the midst of diaper changes and late-night feedings, it’s easy to lose track of how another life is counting on you now. Life insurance is a critical piece of your financial plan that protects your new family in case you die unexpectedly. Here’s why life insurance for new Dads is important, including the four types of life insurance, how much you should buy, and common add-ons you need to know about.
Why New Dads Need Life Insurance
Most people know that they need life insurance, but they’re not exactly sure why. As a new Dad, the importance of life insurance becomes clearer. First of all, you’re now the primary provider for a child for the next 18 years. When we found out that we were pregnant with our first child, I immediately started researching life insurance policies that would cover us until he was in college.
The number one reason to buy life insurance is to replace your income. For working parents, the justification is easy. If you’re a stay-at-home parent, you may think you don’t need to buy a policy. But if you’re gone, who will stay at home with the kids, take them to school, and handle all of the other tasks that you’re doing? Those things cost money, and life insurance helps to pay for them.
Another reason to buy life insurance is to pay off debt. Whether it’s your mortgage, student loans, credit card debt, or other debts, the death benefit from life insurance can eliminate that financial strain. This is especially important if your spouse takes time off to mourn your death and adjust to life without you.
Parents who want their kids to attend college often want to factor tuition, books, and other expenses into their death benefit. While you may hope that your kids qualify for scholarships, it provides reassurance if life insurance provides money towards their degree.
The Four Main Types of Life Insurance
The insurance industry continues to innovate by releasing new products and tweaking existing ones. Through all the changes, there are four main types of insurance that new Dads need to know about.
Term Life
Term life insurance is the cheapest form of life insurance, which makes it an excellent option for new parents. It provides coverage with a constant premium for a set number of years, typically between 10 to 30 years. Once that term expires, the premiums can increase dramatically. For this reason, most people let term life policies lapse after the initial term.
I knew we planned on having two kids, so I bought a 30-year term policy before our first child was born. This would cover both of our kids through college, even if we waited a few years before we had the second.
Whole Life
Whole life is a permanent life insurance policy that is designed to last for your entire life. In reality, the policy matures when you reach either 100 or 110 years, if you haven’t already passed away. At that point, the policy pays out the death benefit.
Premiums for whole life policies are more expensive than term life because of the cash value component. The accumulated cash value allows premiums to stay flat, even as you age and the risk of payout increases.
Universal Life (UL)
Universal life insurance policies offer flexible premiums and death benefits. It is a permanent policy that accumulates cash value and earns interest on the money tax-free. It has two main advantages over whole life insurance. The first is that your cash value can cover premiums if you’re having financial difficulty. Additionally, you can pay extra into the policy to increase the overall death benefit. Some insurance companies allow you to borrow against your cash value with low-cost loans.
When I worked in the insurance industry, I bought universal life insurance to complement my term policy. In addition to the death benefit, this permanent life insurance would provide estate planning assistance and cash value after I retire.
Variable Universal Life (VUL)
Variable universal life offers the same flexibility as universal life. However, instead of placing your cash in stable assets, you can invest in a collection of sub-accounts that mimic mutual funds. This allows for higher growth over time, but does involve the risk of losing cash value if investments underperform.
A VUL is generally not the best choice for new Dads buying their first insurance policy. But it can be a smart choice for high-income Dads who have maxed out their retirement accounts or make too much to contribute to a Roth IRA. I bought a VUL policy for this very reason. It allowed me to contribute extra cash that can grow tax-deferred with tax-free money through loans or the death benefit.
How Much Life Insurance Do You Actually Need?
While you may know you need life insurance, figuring out how much to buy is still a challenge for most new Dads. One rule of thumb is to “10x your income.” If your annual salary is $75,000 per year, then you’d want to purchase $750,000 in life insurance. For many people, this is enough to pay off your mortgage, cover debts like student loans and credit cards, and have money left over for childcare and future education costs.
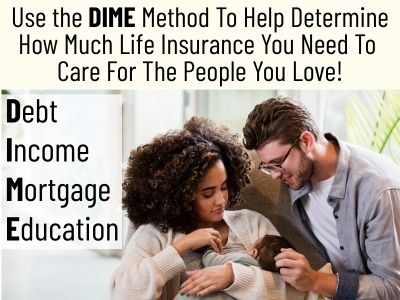
This rule of thumb is very broad and doesn’t take into consideration your personal situation. The DIME Method is a more precise approach to figuring out how much life insurance a new Dad should buy. The acronym DIME stands for debt, income, mortgage, and education, which are the four main reasons why people buy life insurance.
- D – Debt. Add up outstanding debt, including credit cards, car loans, and personal loans.
- I – Income. Multiply your annual income by the number of years your family would need support. For most families, 5 to 10 years of income is adequate.
- M – Mortgage. How much do you need to pay off the remaining mortgage balance so your family can stay in the home?
- E – Education. While future college tuition, room and board, and other costs are hard to gauge, you should plan for $100,000 and $150,000 per child.
Don’t forget burial costs. According to the National Funeral Directors Association, the average cost of a basic funeral with burial is about $8,300.
For a Dad with one child, making $70,000, with a $325,000 mortgage and no other debt, the DIME Method says he should get life insurance between $800,000 and $1,200,000. In my experience working with clients, when premiums are too high for the upper end of their range, I recommend buying a shorter term. Instead of getting a 20 or 30-year term policy, buy one for 10 to 15 years. As your income increases and debt is paid down, you can always replace the policy with a larger one or buy a supplemental policy for an additional amount.
Parents of children with special needs or chronic illness should also factor in the long-term care costs beyond age 18. Who will take care of your child, and what will it cost? Some of these costs are covered by medical insurance and government programs, but families often have to contribute money to their care as well.
Common Riders Worth Knowing About
Most life insurance companies offer add-ons known as “riders” that enhance the features and benefits of our policy. Here are a few of the most common riders that people add to their policies.
- Waiver of Premium Rider. Continues coverage without further premium payments if the insured becomes completely disabled or temporarily unemployed.
- Accelerated Death Benefit Rider. If diagnosed with a terminal illness, the insured can receive a portion of the benefit prior to death. Policies typically allow you to receive 50% of the face amount or $250,000, whichever is less.
- Child Term Rider. Covers children under the policyholder’s policy instead of buying a separate policy. This rider is useful for funeral costs or if a child later becomes uninsurable.
- Guaranteed Insurability Rider. Allows you to purchase additional coverage during a set window without undergoing another medical exam. This is helpful if you’ve had a major life change, like a new child or income increase, but your health would result in higher premiums when buying a new policy.
- Family Income Benefit Rider. Provides the beneficiary with monthly installments equal to the policyholder’s income for a specified number of years, rather than a lump sum.
Keep in mind that each rider you buy increases your premium, sometimes significantly. So, it makes sense to compare policies with and without riders to understand the true cost of insurance. If budget is a concern, focus on getting the death benefit you need rather than loading up on extras and ending up with a lower policy amount.
Review Your Policy Every Few Years
It is important to remember that life insurance isn’t a set-it-and-forget-it decision. You need to review your policy every few years or when major life events occur. Examples include having a new baby, buying a home, a salary increase, getting a divorce, a spouse returning to work, or your child receiving a special needs diagnosis.
Even if you don’t make changes to your death benefit, regular policy reviews ensure that your beneficiaries are up to date. If you get divorced and remarried, your new spouse will be upset if your ex-wife receives the life insurance money instead of her. Additional children could be left out if they’re not added as beneficiaries or if your policy doesn’t specify that proceeds be split among all living children.
The Bottom Line
As a new Dad, it’s time to focus on your financial life and protect your family. Getting life insurance ensures that your family is covered in case you die unexpectedly. The money from the policy can replace your income, pay off debts, cover college education, and so much more. While the 10x Method is a simple approach, I recommend using the DIME Method to my clients so the coverage is personalized to their unique situation and financial goals. While you may be tempted to put off getting life insurance due to cost, there are ways to lower premiums and make them more affordable until your income grows.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- John Hancock, Life insurance: what’s your number? Accessed June 6, 2026.
- Experian, How Much Life Insurance Do I Need? Published July 30, 2025.
- National Funeral Directors Association, Media Center: The Numbers Requested Most. Accessed June 6, 2026.
SelectQuote, Types of Life Insurance Riders: What You Need to Know. Accessed June 6, 2026.