If you have a standard homeowners insurance policy for a house you’re using as an Airbnb or other short-term vacation rental, you may not have the right insurance for your situation. The listing platforms like VRBO and Airbnb offer some protection, but not full coverage. And if a claim is denied, you may have little recourse.
Short-term vacation rental owners may need a commercial policy that covers liability in case a guest is injured, property damage, and business interruption insurance in case you can’t rent out your Airbnb due to damage.
What Airbnb & VRBO Cover for Hosts
Airbnb, VRBO and other short-term rental platforms have their own coverage, often included free of charge to hosts.
Airbnb’s AirCover for Hosts
Airbnb’s liability policy, part of AirCover for hosts, offers $1 million in liability protection if a guest who booked on the platform gets hurt or has their belongings damaged or stolen while they’re staying at your rental.
The company’s Experience & Services liability insurance offers $1 million in coverage if you’re found legally responsible for the guest’s injury or property damage.
AirCover’s host damage protection covers up to $3 million in case your property or belongings are damaged or stolen by a guest during their Airbnb stay.
The policy reimburses you for deep-cleaning, too, to get rid of stains and smells from smoking, spills or pet accidents. The coverage also provides income protection if you can’t rent the property because of the damage incurred.
VRBO Protection
Likewise, VRBO provides $1 million in liability protection if a traveler is accidentally injured on your property or if their belongings are damaged on your property.
Limitations to Airbnb & VRBO Coverage
Airbnb and VRBO’s coverage only applies to guests who book through the platforms. Your property and your guests will not be covered if you accept bookings off the platform or through other services.
These policies also don’t cover damage from natural disasters like fires or storms. They also don’t cover natural disasters that may need an additional policy separate from home insurance, like floods or earthquakes.
Supplemental Coverage
It’s important to understand that VRBO and Airbnb coverage is only supplemental to your own insurance.
Airbnb hosts are required to carry separate liability insurance beyond AirCover. Airbnb’s Experiences & Services liability insurance only provides coverage for damages or injuries when the cost exceeds your liability policy.
VRBO’s coverage works with your other insurance coverage. If your home insurance, general liability insurance or business insurance doesn’t cover the claim, you’ll be required to pay a 25% deductible, according to the VRBO website.
You Have Choices When It Comes to Insurance Protection for Your Short-term Rental
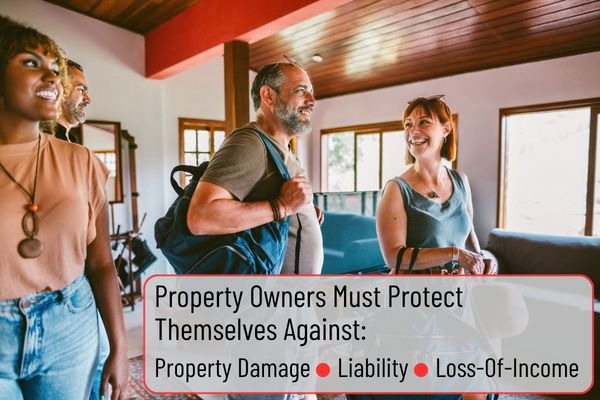
Short-term vacation rental owners need protection above and beyond what the rental platforms provide. You want to make sure you’re covered for any contingency, and that your insurance covers:
- Property damage (your property or your guests)
- Liability (if a visitor, a guest or even a cleaning service is injured on the property)
- Loss-of-income
The type of coverage that will fit your needs and budget depends on how frequently you rent out your property and the home insurance company you currently use. Coverage requirements and available policy options vary by insurer and state.
Homeowner’s Insurance
If you only rent your property as a short-term vacation rental once in a while, and you don’t advertise or accept bookings through the vacation rental platforms, your home insurance policy might cover you.
But, you’ll need to let your insurance company know that you’re renting the place, otherwise they could reject any claims that occur when you have paying guests staying in the home, including damage to their property or to yours.
Home Insurance Endorsement
In some cases, your home insurance company might require a short-term vacation rental endorsement. An endorsement is a rider to your insurance policy that provides additional coverage or lets you customize your policy to better meet your needs.
Be sure to understand exactly what a home insurance endorsement might cover.
It may lack important protections for vacation rental owners, such as:
- Intentional or malicious property damage done by guests
- Pet liability (in case of dog bites, etc.)
- Bed bug and flea protection
- Legal support and lost revenue protection if a guest refuses to leave
- Liquor liability
Landlord Insurance
Some Airbnb and VRBO owners take out a landlord insurance policy. Landlord insurance is designed to protect the dwelling from major perils, like a fire.
But landlord insurance doesn’t cover your guest’s personal property against loss, theft or damage. It may not offer personal injury protection or provide liability protection for short-term guests, either. It’s generally not an adequate option for STR owners.
Short-term Rental Insurance
If you’re operating your short-term vacation rental as a business rather than an occasional side gig, you’ll benefit from a separate short-term rental policy that provides more extensive coverage.
Short-term rental insurance includes multiple components, including commercial liability insurance, coverage for your property and its contents, plus income loss protection. You can purchase separate policies for each type of coverage, or you can roll them together into a short-term rental policy.
Let’s explore the importance of each facet to protect your property and your business.
Commercial General Business Liability Insurance
The liability portion of your short-term rental insurance covers anyone who is injured on your property, regardless of who is at fault.
Building & Contents or Property Coverage
Your STR policy should also cover damage to your building and its contents, as well as any loss or damage to your guests’ property, including luggage and clothing. Look for a policy with replacement cost coverage.
If a guest’s 10-year-old luggage is damaged due to a burst pipe in the vacation home, they will expect to receive enough money to replace it at today’s prices.
This aspect of your policy is similar to parts A, B, and C of home insurance, covering the property, other structures on the property, and personal belongings on the property.
Loss of Income or Business Revenue Protection
If guests bring fleas into the vacation home, you won’t be able to rent the property until you can properly remove the bugs. If the roof of your vacation rental experiences storm damage, you may not be able to rent it out until the roof is fixed.
Both of these circumstances can lead to loss of revenue, especially if you had to cancel on guests who were already booked. A comprehensive STR policy will cover that loss. This is especially important if you rely on your STR as a major source of income.
Bottom Line: Home Insurance vs. Short-term Rental Insurance
You don’t need to purchase a separate homeowners insurance policy for your vacation rental property. Your short-term rental insurance typically covers claims that your home insurance would normally cover, like a tree falling on your property and damaging your fence.
But if your home insurance company finds out you’re renting your home as a short-term vacation rental, they can deny any claims. Home insurance does not cover business property.
When you’re shopping around for an STR policy, find out exactly what’s covered. Some policies may not include flood or earthquake protection. If you live in a region where these natural disasters are common, you may have to add a rider or take out an additional policy.
Shop around for the best rates and the coverage you need before launching your short-term rental business, so that you can be sure you, your guests, and the vacation property are covered.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
https://www.airbnb.com/help/article/279
https://www.vrbo.com/tlp/liability-insurance
https://www.airbnb.com/help/article/1608
https://www.airbnb.com/help/article/1608
https://www.proper.insure/commercial-liability-insurance
https://www.allstate.com/resources/home-insurance/home-sharing
https://www.proper.insure/blog/does-homeowners-cover-short-term-rentals