One of the many benefits of homeownership is the opportunity to make changes to your house to fit your lifestyle. But some home renovations can affect how much you pay for homeowners insurance. Changes like room additions and substantial home improvements can increase your home insurance premiums, while upgrades like monitored security systems may lower your rates.
Understand the Replacement Value of Your Home
When you buy a home with a mortgage, your bank requires you to carry home insurance to protect their investment. Even if you pay cash for your house, it’s a good idea to take out homeowners insurance to protect yourself from liability if someone is injured on your property and to cover replacement costs if your home suffers catastrophic damage. Most policies will even pay for a place to live while your home is being repaired or rebuilt.
Insurance should cover more than just your home’s purchase price. The cost of building materials goes up over time. Replacing your home or repairing damage could cost much more than what you paid for it. When you take out an insurance policy most providers recommend, or even require, coverage of at least 80% of your home’s replacement value.
When you take out a policy with “full replacement value,” your insurance company will pay whatever it costs to rebuild your home after a total catastrophic loss.
But that means if you make improvements or major renovations, it could cost the insurance company even more than expected if you have to file a claim.
We’re not saying you shouldn’t make changes to your home, but you should be aware of potential rate increases. If you think you can just not tell the insurance company, you might get away with it for a little while. But if you have to file a claim, they might not cover additions or renovations that you didn’t report.
By the same token, some improvements can actually reduce your home insurance rates; it’s a good idea to call your insurance company whenever you make major changes to your home.
Home Renovations That Could Raise Your Rates
Of course you want a comfortable, functional home with enough space for your family to enjoy. But be aware that the following changes to your dwelling or property could raise your home insurance rates.
Adding a Second Story or Other Home Addition
If you add to the square footage of your home, it’s most likely going to cost more to replace. That’s why an additional bedroom, another bathroom, or even a whole additional floor or dormer could increase your insurance rates.
Adding or Converting a Garage
Likewise, if you add a garage to your home, whether it’s attached or detached, your insurance is likely to go up. If you convert a garage into living space, you may need permits from your town or municipality. Converting a garage improves the value of your home and increases its replacement value, which could lead to insurance premium increases.
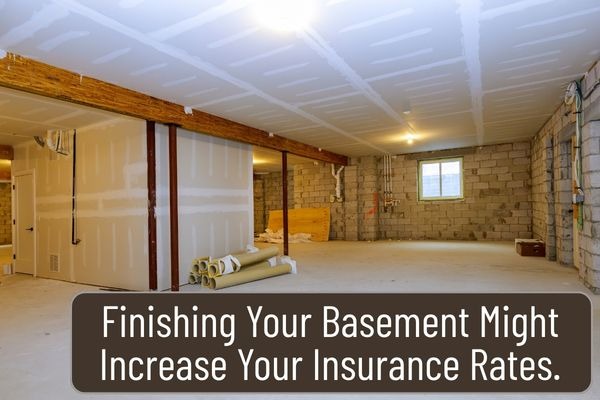
Finishing Your Basement
If you have an unfinished basement and add ceilings, drywall, and floors, you’re increasing your useable living space and raising the value of your home. Your insurance rates might increase.
There are other aspects to consider when you finish your basement, too. Basements are often prone to flooding, which is typically not covered by a standard home insurance policy. To protect your personal property and the basement, you might want to consider adding flood insurance.
Your home insurance company, along with local building codes, may require an egress window that allows for a safe escape from the basement in case of a fire.
Without proper egress in your basement, the insurance company could:
- Deny your claim
- Increase your insurance rates
On the other hand, if you meet local code requirements, you could secure lower rates.
Remodeling Your Kitchen
Modern kitchens feature quartz or granite countertops and stainless steel appliances that may cost more than older kitchen components. Remodeling your kitchen is a costly project that increases your home’s value and, as a result, may increase your home insurance costs.
Adding a Deck
Exterior improvements may also lead to home insurance rate increases. A desk may increase your home’s value. It also may be perceived as a risk by an insurance company, especially if it extends off a second story or is even a few feet off the ground. You might be required to install a railing for safety and to reduce liability.
Adding a Pool or Hot Tub
If add an in-ground or an above-ground pool, your home insurance rates could go up. An in-ground pool, in particular, increases your home’s value, which is one factor. But more importantly, a pool increases the liability risk on your property.
You can mitigate that risk by enclosing the pool within a fence with a locked gate, adding a surface water alarm that alerts you if something or someone enters the water, and always supervising children who are swimming. But the presence of a pool could increase your home insurance premiums even if you take every precaution to keep it safe.
Adding An “Attractive Nuisance” To Your Property
An attractive nuisance is defined as something on your property that could attract curious children and pose a serious danger to them, potentially causing injury or death. When children enter your property because something entices them, they’re no longer treated as trespassers by law.
Examples of attractive nuisances include:
- Playground equipment
- Trampolines
- Abandoned cars
- Treehouses
- Old appliances
- Man-made water features like ponds, fountains or waterfalls (not natural ones)
- Ongoing construction on the property
Home Renovations that Can Lower Your Home Insurance Rates
The good news is that some home improvements can lower your home insurance rates.
A New Roof
I recently saved roughly $620 a year on my home insurance policy for replacing our 20-year-old roof.
That’s in line with industry standards; NBCNews.com reported that the insurance discount for a new roof can range from 5% to 35%. Savings can vary depending on the roofing materials used.
Class 4 impact-resistant shingles, designed to withstand impacts of 2-inch diameter hailstones, can yield the most savings, according to Premier Group roofing company.
To claim the premium discount, you may need to provide a photograph and a receipt.
Storm-protection Upgrades
If you can fortify your home against natural disasters like hurricanes and storms, the insurance company may provide home insurance discounts. Impact-resistant windows
Monitored Home Security and Fire or Smoke Alarm Systems
Home security systems monitored by a third party that alerts local first responders of intruders may result in home insurance discounts of 5% to 20%. Other systems that may lead to discounts include:
- Monitored smoke alarms
- Monitored fire detection systems
- Fire sprinklers
- Water sensors with automatic shut-off
Facing Premium Increases? It Pays to Shop Around
If you’ve made changes to your home and your insurance company suddenly raises your rates, you might save money by shopping around for a new carrier. Insurance companies rarely reward loyalty. Instead, they compete with each other for your business.
If you’re looking for the best insurance rates, make a list of all the discounts you might be entitled to and get quotes from multiple carriers to compare rates.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
https://www.thestreet.com/personal-finance/can-home-upgrades-lower-your-insurance-costs
https://www.progressive.com/answers/does-home-insurance-cover-basement-floods
https://doi.sc.gov/961/Pools-and-Insurance-What-You-Should-Know
https://www.law.cornell.edu/wex/attractive_nuisance
https://www.nationwide.com/lc/resources/home/articles/attractive-nuisances
https://www.cnbc.com/2026/06/02/homeowners-insurance-premiums-costs-how-to-reduce.html