Life insurance is a valuable piece of your estate plan, but most people don’t understand how it can build wealth while you’re alive as well. Term life insurance provides a death benefit to your family when you pass away, but permanent policies build up cash value throughout your life. While cash value life insurance isn’t a replacement for traditional investment or retirement accounts, it is a way for high-income savers to put more money away for the future. Here’s everything you need to know about growing your net worth through life insurance.
Why People Buy Life Insurance
Most people buy life insurance to receive tax-free money to cover major expenses or replace lost income when someone dies. Life insurance is typically purchased or upgraded when you have a baby, buy a home, co-sign for debt, or have a business partner. I bought life insurance when we had our first baby, then increased my death benefit when our second baby was born.
Term life insurance is the most common form of life insurance. It solves the immediate financial need of paying off debt, replacing income, or setting aside money for future expenses. However, once the initial term expires, premiums rise rapidly and become unaffordable.
Permanent life insurance offers coverage that does not expire as long as you keep making payments. Premiums do not increase during your lifetime, so you aren’t priced out of your policy. While premiums are higher, you are building cash value that grows throughout your life. In fact, I advise my high net worth clients to overfund their cash value life insurance to maximize the benefits of their policies.
Term vs. Permanent: Why Only One Builds Wealth
Both term life insurance and permanent policies provide a death benefit to your loved ones when you die. However, these two types of life insurance operate quite differently.
Term life insurance is more like your auto or homeowners’ insurance. You pay for a specific amount of coverage and nothing more. If you stop paying, the coverage expires, and you don’t have any value remaining. For this reason, term is the cheapest form of life insurance you can buy.
Permanent life insurance offers the same death benefit as term, but its cost is substantially higher due to the cash value that you’re building. While the payments are higher, you’re essentially paying yourself by putting money into an account that grows tax-deferred and can be accessed tax-free under the right circumstances.
Most families don’t have adequate life insurance coverage, which is why I typically recommend buying as much term insurance as my clients can afford. If they’re already a high-income earner or as their incomes increase, once their basic insurance needs are met, then I start talking to them about investing in permanent life insurance that builds cash value.
How Cash Value Life Insurance Allows Tax-Free Growth
Cash value life insurance is a blend of term life insurance and an investment account. Your premium pays for both life insurance and deposits to a cash account. While your required premium stays the same throughout your life, you can actually pay extra into your policy to build up your cash value more quickly.
All of the cash in your policy grows tax-deferred. Under the right circumstances, you’ll never pay taxes on this money. These situations include the death benefit and loans against the cash value.
Depending on the policy, as your cash value accumulates, either your death benefit increases or your required premiums decrease. The death benefit increases because your premiums pay for a specific amount of insurance and the cash value adds to the total your beneficiaries receive.
In policies whose death benefit remains the same, premiums may decrease or stay the same because there’s less insurance to pay for as your cash value rises in value. For example, if you have a $500,000 death benefit, you only need to pay for $350,000 in coverage if your cash value balance is $150,000. As it rises to $200,000, then your insurance coverage declines to $300,000.
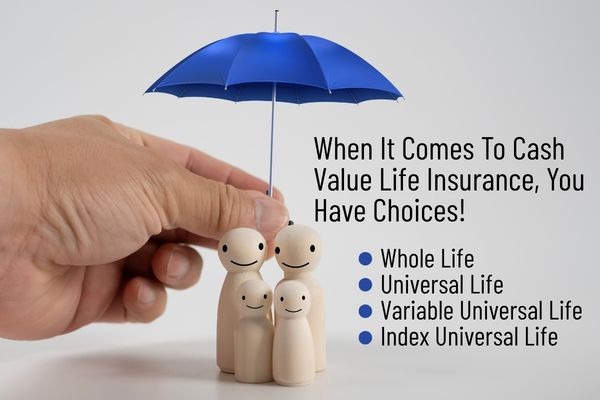
There are four main types of cash value life insurance:
- Whole life. These policies provide a guaranteed fixed growth each year until the policy matures at age 100 or 110.
- Universal life. Offers interest rates that fluctuate based on the economy with no specific maturity date.
- Variable universal life. You choose how to allocate your cash among investments that mimic returns of mutual funds.
- Index universal life. A universal life policy whose returns are linked to indexes with caps and floors on your annual returns.
I have a combination of term insurance and permanent life insurance. The term insurance period correlates to my kids graduating from college. My permanent policies allow me to put away extra cash beyond 401(k) and IRA annual contribution limits.
How Life Insurance Is Used in Estate Planning
Most importantly, life insurance provides a tax-free death benefit to your family when you die. In 2026, the estate tax limit is $15,000,000 per person, which covers life insurance, home values, brokerage accounts, and other assets. If your estate value is above this amount, you’ll pay estate taxes.
For policyholders with estates above the tax limit, I typically recommend purchasing life insurance to cover that tax bill. This ensures that your tax obligations are taken care of without your family needing to sell or dispose of assets to pay taxes on your estate. I’ve seen stories of families having to sell the family business and home or take out loans on debt-free assets to pay taxes when they don’t have readily available cash.
Life insurance is also a way to equalize inheritances to family members. It’s challenging to split a business among children or add an inexperienced sibling into the decision-making process when another child has been involved for years. By purchasing life insurance, you can ensure that all of your children get an equal inheritance or divvy up the money to match your wishes.
An advanced strategy that I’ve used for clients involves irrevocable life insurance trusts (ILITs). These accounts are designed to keep proceeds out of a taxable estate by having the trust own the policy and its proceeds rather than being a part of your individual estate. This reduces your tax bill when the value of your estate (including life insurance proceeds) exceeds the taxable limits.
The Bottom Line
After reading this article, you may be wondering if life insurance is a smart way for your family to build wealth. The life insurance death benefit is a long-term plan to increase your family’s net worth, but you don’t need to wait for death to benefit from life insurance. With cash value life insurance, you can save and invest money without paying taxes on your annual returns. These accounts are not meant to replace traditional investment accounts (like a brokerage, 401(k) or IRA), but they are a smart way to invest additional money to build wealth over the long-term. Their tax advantages, liquidity, and estate planning value make cash value life insurance an integral part of the financial plan for high-net-worth families and people with larger incomes.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- Internal Revenue Service, What’s new — Estate and gift tax. Published February 27, 2026.
- New York Life Insurance, Term vs. Permanent Life Insurance. Accessed July 10, 2026.
- Northwestern Mutual, Understanding the Difference Between Term and Permanent Life Insurance for Your Long-Term Plan. Published June 1, 2026.
- New York Life Insurance, What is an irrevocable life insurance trust (ILIT)? Accessed July 10, 2026.
- Lincoln Heritage Funeral Advantage, How does whole life insurance work? Accessed July 10, 2026.