Your home is probably the biggest financial asset you own, which is why it’s important that it’s adequately insured. While your policy is supposed to protect it, there are hidden gaps in homeowners’ insurance that can leave you at substantial risk. Some of the most damaging losses a home can suffer, like flooding, earthquakes, and valuable jewelry, often aren’t covered the way you’d assume. Here’s why these insurance gaps are important, the five common risks your policy may be missing, and seven ways to ensure you’re covered in case of a claim.
Why These Homeowners’ Insurance Gaps Matter More Than You Think
A homeowners policy is a safety net for your most significant investment. However, in my experience, this insurance leaves major gaps that could surprise you when you need to file a claim. When insurers create policies, they design them to cover a wide range of scenarios, like fire, theft, and wind damage. But they can’t cover every imaginable scenario because then the policies would be too expensive, so they write deliberate exclusions into every standard policy. This way, you’re not paying for coverage that doesn’t apply to your home.
With homeowners’ insurance premiums rising across the country, these gaps matter more than ever. For example, we’re in the middle of hurricane season, and flood damage is one of the biggest and most misunderstood gaps in homeowners coverage. Many of my clients have wrongly assumed they were covered against these natural disasters simply because they had a homeowners’ policy. However, when they needed to file a claim, they discovered that this type of claim was excluded from their coverage.
By reviewing your homeowners’ insurance gaps now, you can figure out how much the extra insurance costs and whether it’s worth paying for. If you wait until your home is in the path of a deadly storm or after it’s been damaged, it’s too late to get the coverage you need to protect your family’s home.
The Coverage Gaps Standard Homeowners’ Policies Rarely Fill
Homeowners insurance handles basic claims well. It covers fire and wind damage to your home and belongings, losses due to theft, and liability if someone gets hurt on your property. However, in my experience, you’re still exposed to several major risks that fall outside standard homeowners coverage.
Flood Damage
Standard homeowners’ insurance excludes flood damage entirely. It doesn’t matter how the water enters your home. If the water comes from the outside, claims are typically handled through flood insurance instead of homeowners’ insurance. For example, flood insurance covers claims due to a rising river, storm surge, or heavy rain that overwhelms the ground around your house. This holds true nationwide, not just in coastal or high-risk flood zones. And even if you think your home is safe from flooding based on its location, that doesn’t mean you won’t need to file a claim.
It’s important to remember that flood coverage is never automatic. You have to buy this policy separately from your homeowners’ insurance. Coverage is available through the National Flood Insurance Program (NFIP) or a private insurer. Some private flood policies now offer higher coverage limits or faster claims handling than the NFIP, so it’s worth comparing both options with your agent.
Earthquakes and Earth Movement
Damage from earthquakes is excluded from a standard homeowners policy nationwide. While most homeowners immediately think of California when it comes to earthquakes, these seismic events are happening more frequently in other parts of the country too. These policies cover other types of earth movement, like landslides and sinkholes, that are more common in other states across the U.S.
If you want this protection, you’ll need to buy a separate earthquake or earth movement policy.
High-Value Personal Property
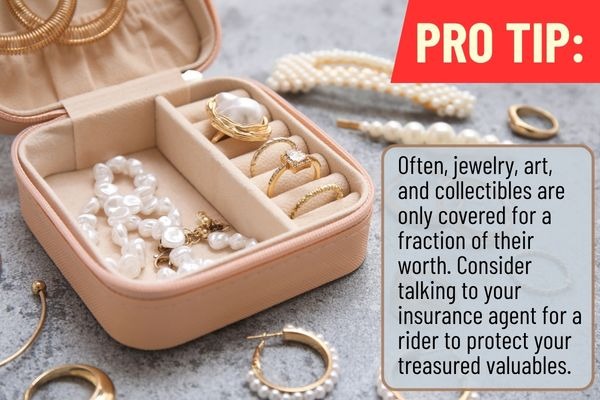
Standard personal property coverage protects everyday belongings like furniture, clothing, and electronics. However, higher-value categories often have sublimits that place a cap on insurance company payouts. In my experience, jewelry, art, and collectibles are often only covered for a fraction of their actual worth. In most cases, policies only cover $1,500 to $2,500. So, if there’s a claim, the majority of your item’s value won’t be covered.
If you have anything that may exceed these limits, talk to your insurance agent about how to ensure it. From my experience, it’s smart to purchase a rider to protect them from damage or theft rather than be left frustrated because your policy payout doesn’t cover the full value. You don’t have to be a millionaire to need additional protection. For example, we added a rider to our homeowners’ policy for the appraised value of my wife’s engagement ring.
Actual Cash Value vs. Replacement Cost
One of the major gaps in homeowners’ insurance isn’t that something is excluded. Instead, it’s that the payout will be substantially less than what it takes to actually replace the item. Standard policies typically default to actual cash value for personal belongings. Actual cash value is what your items are worth today versus what you paid for them as new. Actual cash value reduces the payout by factoring in depreciation for age and normal wear and tear before applying your deductible, which will lower your payout even further.
In my experience, to get an adequate payout to actually replace all of your items, you need to purchase replacement cost coverage. This ensures you have enough to replace your belongings with new or like-new items, even if the cost to buy a new one has increased. With inflation affecting what households pay for everyday items, replacement cost is a smart choice.
Keep in mind that, even with replacement cost coverage, most insurers pay in two steps. First, they pay the depreciated actual cash value of the items claimed. Once you replace the item and submit a receipt, then they send another check to pay the difference. This process is known as “recoverable depreciation.”
I’ve seen homeowners accept that first check and assume that is all the money they’re entitled to. It’s important that their agent or a trusted friend steps in to explain that a second payment is available. However, they need to actually buy the new item to get the additional money.
Uncommon But Important Gaps in Homeowners’ Insurance
A few more gaps in homeowners’ insurance relate to mold, sewer backups, and running a business out of your home. Mold remediation is often excluded outright, so if ventilation is poor and water sits in your home, you’re on your own unless you buy coverage that specifically covers it.
Sewer and water backup typically requires its own endorsement. Many homeowners assume that these are covered by the city or municipal provider, but their responsibilities typically end at the street. The stretch of pipe from your home to their pipes is your responsibility. Buying a separate policy from the utility company or your insurance will protect you in case of a claim.
Big businesses typically have a physical location, yet many small business owners run things out of their homes. Standard homeowners’ policies don’t include business liability or cover your valuable equipment or inventory. To protect yourself, you’ll need to buy a separate policy or an addendum to your homeowners’ insurance. I’ve run my business out of my home for nearly a decade, and it was easy to add coverage to my existing insurance to protect my family and my clients.
How to Close These Gaps in Your Homeowners’ Insurance
You don’t need an entirely new insurance strategy to fix these gaps. A few targeted moves close most of them.
- Buy a separate flood policy. Regardless of whether you’re in a designated flood zone, flood damage is excluded everywhere. I often recommend clients get a quote even if their risk seems low.
- Ask about earthquake or earth movement coverage. People who live in areas with frequent earthquakes, fracking activity, or sinkholes should consider buying a policy.
- Add a Personal Articles Floater or scheduled endorsement. Jewelry, art, collectibles, and other valuables are often above the standard sublimit.
- Upgrade to replacement cost coverage. Take an inventory of your home’s furnishings, appliances, electronics, and other household items to know what you’ve lost. Then, submit receipts for the recoverable depreciation payment after you replace an item.
- Add sewer/water backup and ordinance-or-law endorsements. This is especially important for older homes that need to be upgraded to comply with current building codes after a major repair.
- Tell your agent about any home business or short-term rental use. Don’t assume your policy covers it just because no one told you otherwise. If clients, suppliers, and others come into your home for business purposes, their claims won’t be covered under a standard homeowners’ policy.
- Review your policy annually. Update coverages for the increased value of your home and potential repair costs, especially after a major purchase, renovation, or life change.
Bottom Line
The hidden gaps in homeowners’ insurance are common exclusions found in most policies. Insurance companies offer basic coverages that apply to every homeowner, then keep premiums affordable by excluding risks that affect smaller subsets. Unfortunately, many homeowners don’t realize the gaps until they’re filing a claim. Spend time reviewing your policy with a licensed agent to see which risks apply to your home. Get multiple quotes and compare insurers’ reputations and customer service before switching policies.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- Quartz, 10 things most people don’t know about their home insurance — until it’s too late. Published August 24, 2026.
- Florida Risk Partners, Hidden Gaps in Your Homeowners Insurance: Why Your Valuables May Not Be Covered. Accessed August 31, 2026.
- Pinnacle Risk Solutions, Is your Home Owners Insurance really protecting you? 7 Coverage gaps every homeowner should check. Published July 31, 2026.
- Northeast Insurance Services, Things Your Homeowners Policy May Not Cover. Published September 15, 2025.
- Shafer Insurance Agency, Homeowners Coverage Gaps You Didn’t Know You Had. Published February 12, 2026.