You and your neighbor may share many similarities, yet you could pay vastly different premiums for auto, health, life, disability, and homeowners insurance. It may not seem fair, but there’s always a reason one of you pays less for the same coverage. When an insurance company prices your policy, it estimates how many claims you will file and how much those claims will cost. Depending on the type of insurance, many factors go into pricing a policy. So just because you may seem riskier for one type of insurance doesn’t mean you are risky for another. Learn why insurance companies care about risk and how health, life, disability, auto, and homeowners insurance determine it. I’ll also share nine ways to reduce your risk and lower your insurance rates.
Why Insurance Companies Care About Risk
People buy insurance to cover financial risks, and insurance companies price policies based on how much those claims will be and how often they’ll occur. For example, an auto insurance company doesn’t know whether your car will be stolen this year, but it can predict how many of 100,000 cars will be stolen. This is called the law of large numbers, and it strongly influences insurance premiums.
Once the insurance company estimates how many claims it will pay out, it prices your premium to reflect those costs plus a profit for its shareholders.
The problem insurance companies face is adverse selection. While I believe everyone should have insurance, typically the people who use it most are the ones buying policies, while low-risk people save money by skipping the policy. Policy prices are based on your risk profile rather than charging everyone the same amount. If they priced all customers equally, high-risk people would buy insurance, and low-risk people would not. This is why they want to know so much information about you. When they underwrite your application, they place you in a pool of similar risk and price the policy based on how much they expect to pay out. I know it’s annoying to fill out these application questions, but your answers help ensure you pay a fair price for your coverage.
How Insurance Companies Determine Risk
All insurance companies underwrite your application, and then rate you based on your answers. However, each type of insurance looks at different information when determining how much you’ll pay.
Health Insurance
Health insurance differs from other types because of regulations set by the federal government. They are only able to base your rate on five factors.
- Age. Your rate can be no more than three times what someone half your age pays.
- Where you live. Rates can vary by area due to competition and the cost of medical care in your state.
- Tobacco use. Your rate can be increased by 50% if you smoke. Keep in mind you will not receive a premium tax credit for this extra amount.
- Individual, couple, or family policy. Your rate will be higher if you add a spouse or children.
- Level of coverage. A bronze plan costs less per month than a gold or platinum plan.
Insurance companies cannot increase your rate based on your health history or gender. Some states don’t allow age to factor into your rate, including New York and Vermont.
Life Insurance
Life insurance companies try to estimate how long you will live, which determines how long you’ll pay premiums before they have to pay out. The insurer also uses this information to determine how many policyholders will pay premiums but stop paying before being able to collect on the policy. For example, someone who is 80 years old is more than 60 times more likely to die than someone who is 20 years old. They will also look at your medical history, height and weight, blood work, family history, smoking, driving record, and hazardous hobbies when pricing a policy. In my experience, I’ve seen some insurers consider how much and where you travel when setting premiums.
After they collect this information, they place you in a risk class. There are usually four risk classes for non-smokers and two risk classes for smokers. If you have some serious health issues, you may get table rated at a higher premium or denied coverage.
Today, most life insurance companies don’t require a physical to qualify for coverage unless you want a large death benefit. Instead, they use accelerated underwriting. This means they have access to your prescription history, driving record, and Medical Information Bureau (MIB) records. The MIB database holds information that was disclosed when applying for life insurance in the past. When I sold life insurance, omitting this information on your application was one of the biggest red flags when applying for a policy or when your beneficiaries file a claim after you die.
Disability Insurance
Like life insurance, disability insurance predicts if you will become disabled and how long you’ll be out of work. Your occupation plays a huge role in how much you pay because insurance companies classify jobs and assign them a risk level. For example, an accountant is less likely to become disabled than a roofer. As a result, you may have to pay more or accept a shorter benefit period if you are in a high-risk classification. Your health history and hobbies also affect rates and whether the insurer declines your application.
Your income is another factor because it determines how much the insurer has to pay out when there’s a claim. While disability insurance typically replaces 60% to 90% of your income, someone with a $100,000 salary will receive a higher payout than another person making $60,000. In my opinion, disability insurance doesn’t cover your full salary because it incentivizes you to return to work.
Auto Insurance
Auto insurance companies try to predict how many claims you will file and how much they’ll cost. Your driving record is the biggest factor, but your age, driving experience, and car type also play a big role. Where you live matters because of accident risk, repair costs, and how often cars are broken into locally. They usually look at the past three to five years of driving, so if you’ve had accidents or claims long ago, they typically won’t affect your premiums. Your age and time driving also play a role.
Your credit score also affects your rate in many states, but others don’t allow credit to impact your premiums. In states that allow it, people with bad credit typically pay about 105% more than someone with good credit. Learn more about how credit scores affect your insurance premiums.
Telematics is changing how insurance companies price premiums. When you install a telematics device or mobile app, the insurer can monitor your annual mileage, how fast you drive, how hard you brake, and if you use your phone while driving. For many drivers, telematics is an easy way to save money on auto insurance. But I always remind my clients to decide whether giving up some privacy is worth the savings.
Homeowners Insurance
Homeowners insurance covers the risk of damage to your home. When setting rates, where you live is the number one factor. Homes in high-risk areas, like Tornado Alley, California, or Florida, can cost up to 50% more than the national average. As climate change continues to affect us, these rates will keep increasing in some states. When the risk becomes too great, insurers may leave the market or stop issuing new policies.
Your proximity to a fire station can lower or increase your premiums, since the time it takes the fire department to arrive can mean the difference between a little fire damage and a total loss. Liabilities on your property can affect rates. A pool, trampoline, or certain dog breeds often lead to more claims against a policy.
The cost to rebuild your home, the materials it’s made of, and upgrades to your home are other factors that impact premiums. The age and materials of your roof play a big role in your homeowners rate. Wind and hail claims are the most expensive losses for insurance companies.
An insurer will also look at your CLUE report (Comprehensive Loss Underwriting Exchange). It is a database of past claims related to you or your home, so your rate could be higher because a previous owner filed a claim on your home.
What are Insurance Companies Looking For?
| Policy | What They’re Predicting | Biggest Factors | What You Can Control |
| Health | Your medical costs | Age, location, tobacco use | Tobacco use, plan category |
| Life | When you’ll die | Age, health, tobacco, hobbies | Health, tobacco, when you buy |
| Disability | Whether and how long you can’t work | Occupation, income, health | Health, hobbies, when you buy |
| Auto | How often you’ll file claims and their cost | Driving record, credit, ZIP code, vehicle | Driving habits, credit, vehicle choice |
| Homeowners | Damage to your property | Location, roof, rebuild cost, claims history | Roof, home upgrades, small claims |
How to Reduce Your Risk and Lower Your Rates
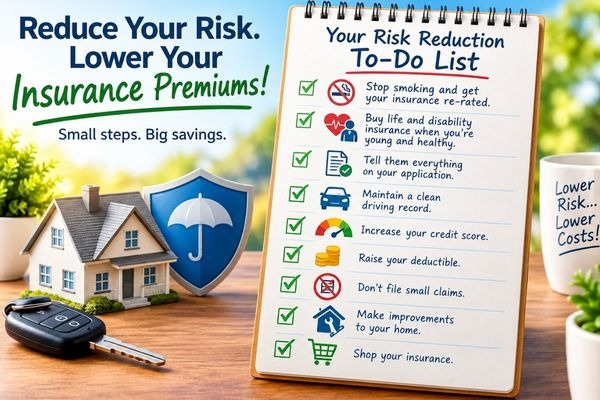
Insurance companies focus on the risk of claims when setting rates. You can’t change how old you are, where you live, or your family health history, but you can take simple steps to reduce your risk and lower your premiums.
- Stop smoking and get your insurance re-rated. Smoking will increase your rate on health, life and disability insurance. Once you have met your non-smoker requirements, contact your insurance company and get re-rated.
- Buy life and disability insurance when you’re young and healthy. Your rate is determined when you purchase the policy. If you develop a health issue down the road, you will stay in that risk class.
- Tell them everything on your application. A rated policy that will pay is better than a cheaper policy that won’t.
- Maintain a clean driving record. Take a defensive driving course and enroll in a telematics program if you drive safely.
- Increase your credit score. A higher credit score can lower your auto and homeowners insurance rate.
- Raise your deductible. Since you’re taking on more risk when you file a claim, insurance companies will reward you with a lower rate.
- Don’t file small claims. Consider paying for small claims out of pocket when you have a higher deductible. Make sure you have an emergency fund that you can use to cover these small claims.
- Make improvements to your home. A newer or impact-resistant roof, water leak sensors, and a monitored alarm can all earn discounts.
- Shop your insurance. Different insurance companies will weigh these factors differently, and their formulas can change regularly. You may find cheaper insurance somewhere else, even if you changed policies just a few years ago.
We have a monitored home alarm that includes fire detectors, door sensors, and a water sensor near the hot water heater. These simple add-ons protect our home and provide a discount on our homeowners insurance.
The Bottom Line
Insurance companies base premiums on how much a claim will cost and how often they’ll occur. The formula and factors used to set rates vary by company and policy type. Some consider your health or driving record, while others focus on where you live or how much you make. Some factors you cannot control, but you can reduce your insurance premiums by changing the ones you can. Review your policies regularly to determine how much coverage you need and if anything has changed that could lower your rates. Compare rates once a year, and consider working with a licensed insurance agent who can shop multiple carriers at once.
The information provided on this website is for general informational and educational purposes only and should not be considered legal, financial, or insurance advice. While we strive to keep content accurate and up to date, insurance laws, policies, and regulations can vary by state and may change over time.
Nothing on this site constitutes professional advice or a recommendation of any specific insurance product, provider, or strategy. You should consult with a licensed insurance agent, financial advisor, or legal professional regarding your individual situation before making any decisions.
Sources
- National Institutes of Health, State policies limiting premium surcharges for tobacco and their impact on health insurance enrollment. Published October 27, 2020.
- Our World in Data, Annual death rate by age group. Accessed October 12, 2026.
- Investopedia, Maximum Disability Insurance Coverage: What You Need to Know. Published November 21, 2025.
- Society of Actuaries, A Decade into Accelerated Underwriting: The New Normal for Advanced Risk Selection. Published August 2023.
- Open Exam Prep, Underwriting Process, Risk Classification, and MIB. Published June 2026.
- USAA, Factors that affect your home insurance rates. Published August 31, 2026.
- Verisk, Make confident decisions about property risk. Accessed October 12, 2026.
- Automotive Addicts, Key Factors That Affect Car Insurance Rates. Published February 25, 2022.